News
In Riyadh, Buhari urges leaders to invest in global security policies
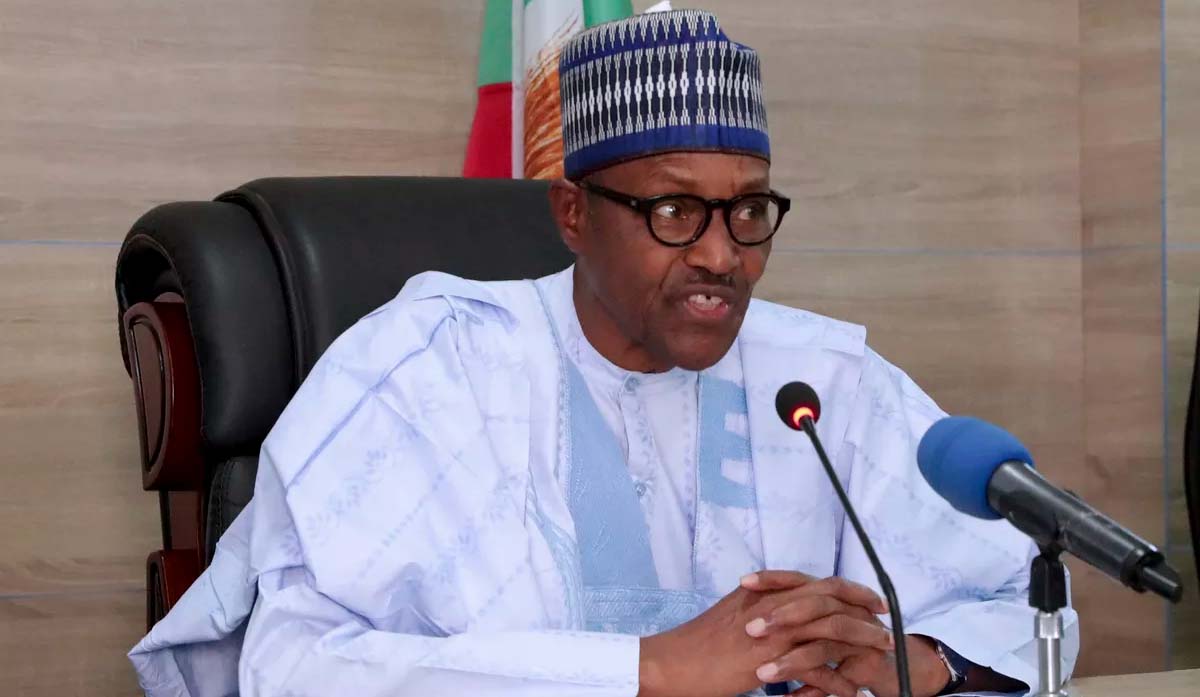
President Muhammadu Buhari has called on world leaders and investors to devote more energy to the advancement of humane policies and practices that will guarantee global peace and stability. Buhari said this would help in addressing the rising tension and violence across the world.
Buhari stated this in Riyadh, Saudi Arabia, on Tuesday at the opening of a three-day “Future Investment Initiative Summit.”
He canvassed debt relief for struggling economies, especially, in the wake of the COVID-19 pandemic.
Buhari stressed that the rising global social unrest was caused by deteriorating social inequalities and unfair distribution of wealth and resources, which according to him, denied the majority the opportunity to participate.
He said the only way to prevent further escalation of global social unrest was for both governments and private sector stakeholders to start engaging in “humane investments,” which would factor the majority into the growth and development loop.
The president said his administration would keep encouraging public and private initiatives to increase investments in health, education, capacity building, youth empowerment, gender equality, poverty eradication, climate change, and food security.
“By so doing,” Buhari stated, “it will go a long way in re-energising the global economy in a post COVID-19 era.”
READ ALSO:
https://newstrends.ng/2021/10/27/tinubus-capable-of-leading-nigeria-south-west-govs/
He explained, “Nigeria is Africa’s largest economy and most populous nation. Our economic reforms, which focus on ‘humane’ investments, are ideal for investors looking to have profitable returns while positively impacting the citizenry.
“Investing in humanity is the right thing to do. I strongly believe the historical under-investments in ‘humane projects’ is the genesis of most of the insecurity and socio-economic challenges the world is experiencing today”.
Speaking on the theme of the summit, “Investing in Humanity”, Buhari said the Nigerian perspective was to focus on people-oriented development policies, with diversification from oil to more inclusive sectors, such as agriculture, Information and Communications Technology (ICT), and mining. He said his government was also channelling its energies into tackling corruption, insecurity, and climate change, as well as introducing social investment programmes.
Buhari stated, “Investing in humanity is investing in our collective survival. This is why we in Nigeria believe that public and private partnership should focus on increasing investments in health, education, capacity building, youth empowerment, gender equality, poverty eradication, climate change and food security.”
The president also told the audience, “Nigeria’s population today exceeds 200 million people. Some 70 per cent are under 35 years old. When we came into government in 2015, we were quick to realise that long-term peace and stability of our country is dependent on having inclusive and humane policies.
“In the past six years, our government took very painful but necessary decisions to invest for a long-term prosperous future, knowing very well that this will come with short term pains.”
He emphasised that humane investment practices were the only way to address the global challenges the world currently faced following the pandemic.
According to him, “We should continue to sustain our efforts to combat the COVID-19 pandemic and mitigate its negative socio-economic impact on our societies, build resilience and achieve recovery.
“It is, therefore, my hope that this session will leverage on the enormous economic opportunities that lie ahead in order to satisfy the prevailing needs of our people and planet.”
The president stated that investment in humanity must also take into consideration the debt burden on nations, which had been worsened by the COVID-19 pandemic.
He said, “We cannot invest in humanity without relieving our countries from the crushing effects of the debt burden, especially, when the COVID-19 pandemic has increased the risk of deepening the debt portfolio of poor countries.
“These nations increasingly allocate more and more resources towards external debt servicing and repayment at the expense of the health, education and other services that contribute to the overall wellbeing of their populations.”
Buhari told the gathering that Nigeria’s diversification effort had continued to yield result, particularly in agriculture.
He disclosed, “We introduced policies that supported investments in agriculture and food processing. We provided loans and technical support to smallholder farmers, through the Anchor Borrowers Programme.
“As a result, Nigeria today has over 40 rice mills from less than 10 in 2014. Nigeria also has over 46 active fertiliser blending plants from less than five in 2014.
“Furthermore, in agriculture, we have reformed the process of obtaining inputs, such as fertiliser and seeds. We have several million hectares of available arable land and have embarked on the creation of Special Agriculture Processing Zones across the country. These initiatives we believe will make it easier for investors in agriculture.”
The president said the oil sector was undergoing a reform that would make it more attractive and inclusive.
He told the global investment public, “Two months ago, I signed the Petroleum Industry Act. The Act will serve as a catalyst to liberalise our petroleum sector. It has introduced a number of incentives, such as tax holidays, 100 per cent ownership, zero interest loans, and easy transfer of funds. In addition, we have highly skilled in-country workforce and a large domestic market.
“In mining, we have also made several opportunities available for investors. Nigeria is a country rich in minerals from gold, iron ore, tin, zinc, cobalt, lithium, limestone, phosphate, bitumen and many others. We have made the licensing process easier and also made extensive investments in rail and transportation.
“Infrastructure investments represent significant potential for investors in Nigeria. We have opportunities in seaports, rail, toll roads, real estate, renewable energy and many others. We have created several institutions that are available to co-invest with you in Nigeria.
“We have the Nigeria Sovereign Investment Authority and more recently, I approved the creation of Infrastructure Corporation of Nigeria. These institutions are run as independent world-class institutions to make investments in the country and are available to co-invest with you.”
He called for more interest in infrastructure, such as healthcare and education, which “present enormous opportunities for investors in a country our size.”
Buhari said, “Digital Economy in Nigeria has many potentials for investment, as it has remained the fastest growing sector in both 2020 and 2021. Nigeria has many opportunities for investment in broadband, ICT hardware, emerging technology and software engineering.
“We have recently approved the national policy on Fifth Generation (5G) network. Our aim is to attract investors in healthcare, smart cities, smart agriculture among others. The benefit of real time communication will support all other sectors of the economy.”
As a means to further improve and reposition Nigeria’s economy to attract investors, the president said the, “e-Naira, the electronic version of our national currency, which puts us on track to become the first African country to introduce a Central Bank Digital Currency,” was launched on October 25.
He said, “We believe this and many other reforms will help us increase the number of people participating in the banking sector, make for a more efficient financial sector and help us tackle illicit flow of funds.
“To further strengthen our anti-corruption drive, increase accountability and transparency, we have centralised government funds through a Treasury Single Account, and ensuring that all Nigerians with a bank account use a unique Bank Verification Number (BVN).
“These initiatives, coupled with our nationwide National Identification Number (NIN) exercise, reinforce our efforts to tackle corruption and fraud. We believe that this should give investors a lot of comfort.”
He also told the world leaders about the devastating effect of climate change on livelihoods of people around the Lake Chad.
He added, “As we strive to build resilience towards a sustainable economy in our various countries, let us not forget the negative impact of climate change on our efforts to achieve this goal. Nigeria and many countries in Africa are already facing the challenges posed by climate change.
“Climate change has triggered conflicts, food insecurity, irregular youth migration, rising level of sea waters, drought and desertification, as well as the drying-up of the Lake Chad.
“In the Lake Chad Basin region, where Boko Haram insurgency continues to undermine the peace, security and development of the region, climate change is largely responsible for the drying up of the Lake Chad, which has shrunk by more than 85 per cent of its original size.
“The diminishing size of the lake is at the root of the loss of millions of livelihoods, displacement of inhabitants and radicalisation of teeming youths in the region who are recruited to serve as foot soldiers in the insurgency.
“In order to redress this situation and restore the lost fortunes of the Lake Chad Basin region, strong public-private partnership through massive investments will be needed to recharge the waters of Lake Chad. I am confident that this forum will rise to the challenge in the interest of durable peace and sustainable development of our region.”






News
NBS: Nigeria’s Inflation Slips to 15.39% in August
NBS: Nigeria’s Inflation Slips to 15.39% in August
Nigeria’s inflation rate eased to 15.39 per cent in August 2026 as the pace of price increases slowed across the economy, the National Bureau of Statistics has reported.
The latest Consumer Price Index report shows a modest fall from the 15.43 per cent recorded in July.
A sharper improvement was recorded in monthly inflation. The rate dropped from 1.57 per cent in July to 0.71 per cent in August, meaning prices continued to rise but at a much slower pace.
Food inflation also slowed significantly.
The NBS put year-on-year food inflation at 19.57 per cent in August. This was below the 25.30 per cent recorded a year earlier. Monthly food inflation also fell sharply, moving from 5.56 per cent in July to 1.02 per cent in August.
The statistics agency attributed the monthly decline to lower average prices for a range of food products, including palm oil, pepper, onions, cassava flour, beef, yam flour, egusi, ginger, fresh fish, Irish potatoes, chicken and turkey.
The improvement, however, was not shared equally across the country.
Adamawa had the highest annual food inflation rate at 38.85 per cent. Zamfara followed with 37.96 per cent, while Bayelsa recorded 36.20 per cent.
At the other end, Borno recorded negative annual food inflation of -4.04 per cent. Jigawa recorded -0.23 per cent, while Kebbi stood at 3.47 per cent.
For monthly food inflation, Katsina recorded the highest rate at 9.48 per cent, followed by Rivers at 8.86 per cent and Osun at 8.32 per cent.
The latest figures suggest a broad slowdown in price growth, although the wide differences between states show that many households are still facing very different food price pressures depending on where they live.
NBS: Nigeria’s Inflation Slips to 15.39% in August
metro
Fatal NURTW Leadership Clash in Osun Leaves Two Dead; State Orders Park Shut Down
Fatal NURTW Leadership Clash in Osun Leaves Two Dead; State Orders Park Shut Down
As Olalekan Oyeyemi is buried in Osogbo, authorities transfer murder probe to the State Criminal Investigation Department.
News
Peter Obi Rejects Anambra Debt Claims, Challenges Soludo Govt to Produce Evidence
Peter Obi Rejects Anambra Debt Claims, Challenges Soludo Government to Produce Evidence
Former Anambra State Governor and 2027 presidential candidate Peter Obi has rejected claims that he left the state with unpaid financial obligations when he handed over power in 2014, challenging the Anambra State Government to identify any contractor, supplier, worker or pensioner who was owed money by his administration at the time.
Obi made the statement in response to renewed claims by the administration of Governor Chukwuma Soludo that the state is still servicing loans and other financial obligations inherited from previous administrations.
The dispute has opened a fresh political debate over Anambra’s debt profile, the financial obligations inherited by successive governments and the management of the state’s resources before and after Obi left office.
Obi, who governed Anambra between 2006 and 2013 before handing over to his successor in 2014, said he paid what was due during his tenure and left the state in a financially stable position.
He challenged the Soludo administration to provide evidence of any unpaid obligation incurred by his government that remained outstanding when he left office.
According to Obi, if the state government can identify any contractor, supplier, employee, pensioner or other beneficiary who was owed money by his administration at the time of the handover, he would be prepared to address the matter.
The former governor also said his administration left funds in government accounts, including an alleged ₦2.14 billion ecological fund balance, when he handed over power.
However, the claim regarding the ecological fund is from Obi’s camp and would require confirmation from the relevant official financial records.
READ ALSO:
- Peter Obi: Release My UNN Academic Records, I Have Nothing to Hide
- A Son Wouldn’t Have Done Better — Dangote Speaks on Daughters, Succession
- 2027: APC Governors Reject Wike’s Rainbow Coalition, Insist on Party Loyalty
The response followed comments by the Anambra Commissioner for Finance, Izuchukwu Okafor, who said the state was still repaying loans inherited from previous administrations.
Okafor said the Soludo administration had not obtained any commercial bank loan since it came into office in 2022, arguing that the government’s focus had been on reducing the state’s inherited financial obligations.
He said the state’s debt burden had been substantially reduced under Soludo and that the administration had also cleared inherited liabilities relating to contracts, gratuities and pensions.
The commissioner said some loans taken by previous administrations remain subject to repayment and deductions from the state’s federal allocations.
This distinction is at the centre of the current disagreement.
The Soludo administration is not necessarily claiming that Obi personally left unpaid bills to contractors or workers. Rather, the government is pointing to loans and other financial commitments inherited from successive administrations, some of which continue to be serviced.
Obi, on the other hand, is arguing that his administration settled the obligations that were due and payable when he left office and should not be held responsible for liabilities incurred by subsequent governments.
The issue has therefore raised questions about the difference between a state’s overall outstanding debt and debts that were specifically incurred by an individual administration.
Available public debt records have shown that Anambra had outstanding formal obligations around the period Obi left office. However, the political dispute centres on when particular obligations were incurred, which administration contracted them, when repayment became due and whether they should be described as unpaid debts inherited from Obi’s administration.
The Soludo administration has maintained that it inherited financial commitments from previous governments and has been working to reduce them.
The finance commissioner reportedly said the state’s domestic debt was now close to zero and that the government had reduced its overall debt burden significantly.
He also said the Soludo administration had not resorted to commercial bank borrowing since assuming office, presenting the reduction in liabilities as evidence of improved fiscal management.
The government has simultaneously highlighted investments in infrastructure and other projects while maintaining that debt reduction remains an important part of its financial strategy.
READ ALSO:
- Sanwo-Olu Joins Dangote as Historic N2.15tn Refinery IPO Opens on Nigerian Exchange
- Shehu Buba Submits Himself To DSS Over Banditry Allegations
- No Lives Lost as Responders Contain Dual Fire Outbreaks Across Lagos
Obi’s camp, however, has questioned the basis for attributing current financial obligations to his administration.
The former governor has repeatedly presented his tenure as one characterised by fiscal discipline, savings and investment in infrastructure, education, healthcare and other sectors.
His supporters have pointed to the savings and financial reserves accumulated during his tenure as evidence that the state was handed over in relatively strong financial condition.
Critics of the former governor, however, argue that the financial position of a state cannot be assessed solely by looking at cash balances or the absence of unpaid bills because governments can inherit long-term obligations whose repayment extends beyond the tenure of the administration that contracted them.
That distinction is particularly relevant in Anambra, where governments have succeeded one another while continuing to service financial commitments made over several administrations.
The latest exchange has consequently shifted the political conversation from whether Anambra has debt to the more specific question of which administration incurred particular liabilities and whether those obligations were outstanding at the time of each handover.
The dispute also comes at a politically sensitive period, with Obi preparing for the 2027 presidential election under the Nigerian Democratic Congress (NDC).
Questions about his record as Anambra governor are likely to remain part of the political debate as the election approaches, particularly because his administration’s economic management has been a central part of his political narrative.
For Soludo, who is serving as Anambra governor, the emphasis has been on the state’s current fiscal position and the steps his administration says it has taken to reduce inherited liabilities while funding development projects.
For Obi, the priority is to establish that he did not leave unpaid obligations to contractors, workers, pensioners or other beneficiaries when he left office.
The former governor has therefore challenged the state government to publish specific records showing any outstanding obligation attributable to his administration at the point of handover.
The competing claims have yet to be resolved by an independent audit or judicial determination.
What remains clear is that Anambra’s debt debate involves more than a simple disagreement over whether the state owes money. It encompasses loans contracted by successive administrations, repayment schedules, inherited liabilities, outstanding contracts and the question of how political leaders should be held accountable for financial commitments made during their tenure.
As the exchange continues, official debt records, audited financial statements and handover documents could provide the clearest basis for determining the extent of liabilities inherited by each administration.
Until such records are independently reviewed, claims that Obi either left the state completely debt-free or was solely responsible for all of its inherited obligations should be treated with caution.
The latest dispute therefore leaves two competing narratives: Obi’s insistence that he paid what was due before leaving office, and the Soludo administration’s position that Anambra continues to service financial obligations inherited from previous governments, including loans dating back to earlier administrations.
With the 2027 election approaching, the controversy is likely to remain part of the wider political contest over Obi’s record in Anambra and his claims of fiscal discipline in government.
Peter Obi Rejects Anambra Debt Claims, Challenges Soludo Government to Produce Evidence
-
 News3 days ago
SERAP Threatens Legal Action Over ₦126bn INEC Electoral Funds
-
 Politics3 days ago
Five Islamic Clerics Abducted After Tinubu Re-Election Prayer At Yari’s Zamfara Residence
-
 Opinion3 days ago
‘Tinubu Will Win Again in 2027’ — Charismatic Bishops’ Secretary
-
 Politics1 day ago
2027: Northern Lecturers Back Tinubu, ASUU Disowns Endorsement
-
 metro3 days ago
Mother ‘sold daughter’s abuse videos for $300’: Nigeria child pornography case shocks nation
-
 Sports3 days ago
‘Unacceptable’ — Arteta Furious Over Sunderland Penalty in Arsenal Win
-

 News3 days ago
Petrol Subsidy: Presidency Rejects Atiku’s Plan, Says No Going Back
-
 International3 days ago
US Blockade Tightens As CENTCOM Redirects 100 Commercial Ships From Iranian Ports