Business
Doubts as Nigeria negotiates debt relief with World Bank, IMF

• Owoh: It’s fruitless, costly effort to further defraud citizens • Economy risks junk status, experts warn
• Country faces hard, painful choices, says Oxford economist, Dercon
• El-Rufai admits NNPC hasn’t brought N20,000 to nation’s treasury in 2022, says it’s a failure
During a media interview on the sidelines of the ongoing World Bank and International Monetary Fund (IMF) Annual Meeting on Wednesday, Ahmed said FG had commenced discussions with the Bretton Wood institutions on debt restructuring for the country.
“It is a fact that Nigeria’s debt has increased over the last three to four years and this increase in debt was occasioned by the different kinds of exogenous shocks that the country faced, which are not unique to Nigeria. The situation we have by the 2023 projection is that we will need about 65 per cent of our revenues to service debt.
“Unfortunately, the cost of debt service is rising, because of the growing interest rate globally, which is resulting also in higher debt service costs. But our projection from the debt sustainability analysis is that Nigeria is able to cope with its debt service in 2022 as well as in 2023.
“We have been engaging financial institutions to look at the opportunity to restructure our debt to further stretch the debt service period to give us more fiscal relief. Those are some of the things we want to achieve in this meeting,” Ahmed said.
READ ALSO:
- Ogun man kills wife, burns corpse with iron
- How I was framed for armed robbery, dumped in prison — 32-yr-old painter
- 2023: It’s reward time for Tinubu, say Kwara governor, senator
The official disclosure came same day Managing Director of Augusto & Co, Olabode Augusto, raised the alarm that Nigeria was on “its road to Zimbabwe,” stressing that no other country is leveraging 10x spending as the country is currently doing. Leverage ratio is the level of debt in proportion to income or equity.
According to Augusto, crisis-ridden Sri Lanka and neighbouring Ghana, which is seeking debt restructuring, have a leverage ratio of 7x and 3x respectively.
While Ahmed is in Washington negotiating with development partners, one of the world’s most renowned economist and Director of the Centre for the Study of African Economies, University of Oxford, Prof. Stefan Dercon, is in Nigeria to speak on the state of the economy and the options before the managers.
On Wednesday, Dercon dismissed Nigeria as a country trapped in an ‘elite bargain’ crisis. He said hard choices would be able to rescue the economy but warned that even choices are limited in these hard times. He said any decision taken to achieve macroeconomic stability would be painful. The best time to act was about seven years ago, he said, advising the country to continue to manage the situation but show commitment to making hard decisions when things are more stable.
Reacting to the Minister’s disclosure, a professor of economics and debt management expert, Godwin Owoh, described the plan as another fruitless and costly ploy that would further drain public purse. He challenged government to provide more information about the consultants it is working with to help Nigeria evaluate the process.
“Who are the consultants they are working with? What are their terms of reference?” Owoh asked, saying there is little room for negotiating restructuring of the country’s debt. He said some of the debts are still shrouded in secrecy, adding that debt restructuring negotiation can take up to a year, which the current administration does not have the luxury of time to see the process through.
Chief Executive Officer of Dairy Hills Limited, Kelvin Emmanuel, warned that the move would downgrade the country’s economy to ‘junk status’, which would mean that the country will no longer be creditworthy in the international market.
Emmanuel also argued that converting the ways and means (W&M) facility into local debt stock is not only a violation of the Central Bank of Nigeria (CBN) Act, but would also increase the total debt stock by over 50 per cent and worsen the cost of servicing; as well as trigger a downgrade to a lower rating from the current not-too-good B2.
READ ALSO:
- Buhari Approves 12,000 Metric Tons Of Grains For Flood Victims
- Why we quashed terrorism charge against Nnamdi Kanu — Appeal Court
- Governor Sanwo-olu signs MoU with Del-York to build media, film city in Lagos
“Seeking to raise $20 billion is proof that the government does not understand the impending doom the economy faces in the current trajectory,” he said.
President Muhammadu Buhari had at the United Nations General Assembly in September sought the assistance of world leaders in considering granting debt relief or outright cancellation to developing countries.
But the Deputy Managing Director of IMF, Kenji Okamura, has urged governments to be prudent and spend public resources for the greater need of the people.
He said: “We live in turbulent times, which highlights the importance of social contracts – an understanding of mutual expectations that bind citizens and their governments. To strengthen public trust and support social cohesion, governments need to invest in basic public services and deliver more inclusive policies. Fair and more transparent use of public resources is key.”
At a press conference, yesterday, the Managing Director of the Fund, Kristalina Georgieva, appealed to policymakers to act with a sense of urgency to bring down inflation and support vulnerable emerging markets.
The statement came shortly after the reading of the United States’ September Consumer Price Index (CPI), which showed a slight decline, but higher-than-expected inflation. The inflation rate slowed to 8.2 per cent from 8.3 per cent in August.
Georgieva said policymakers need to act now and act together in resolving inflation and safeguarding financial stability. On this note, she said, macro-prudential policies need to be vigilant and proactively address pockets of vulnerability.
“In this environment, we also must support vulnerable emerging markets and developing countries. It is tough for everybody, but it is even tougher for countries that are now being hit by a stronger dollar, high borrowing costs, and capital outflows, a triple blow that is particularly heavy for countries that are under a high level of debt.”
MEANWHILE, Kaduna State governor, Nasir Ahmed el-Rufai, has restated that the Nigerian National Petroleum Company Limited (NNPCL) is a big problem to Nigeria, and unless it is completely sold, it is capable of bringing the country to its knees.
In the build up to elections of 2015, el-Rufai and the All Progressives Congress (APC) promised to reorganize the corporation but a few months to the departure of this administration, the lamentation has not changed.
READ ALSO:
- UNILAG tops Nigerian varsities, makes 401-500th global ranking
- Court acquits ex-Jigawa Governor Turaki of N8.3b fraud
- BREAKING: ASUU Finally Suspends Strike
The governor, who stated this while speaking on Channels Television special programme to mark the beginning of the yearly Kaduna Investment Summit (KADInvest 7.0), said the Federal Government has failed in the oil and gas business and should get out of the sector.
El-Rufai, while speaking to the theme of the summit, ‘Building a Resilient Economy,’ stated that since the beginning of this year, NNPCL has not brought even N20,000 to the Federation Account.
According to him, “NNPC is a big problem to Nigeria and unless we resolve it, it will bring Nigeria to its knees. It is a systemic and institutional problem, it is beyond one person.”
He said: “There is no reason why government should still be in the oil and gas sector. It should just get out, it has failed. By every measure it has failed.
“When I say the Federal Government should get out of oil and gas, people shouldn’t think it’s crazy, it’s not. We are living on taxes. It is PPT, royalties and income tax that is keeping this country going, because NNPCL claims that subsidy has taken all the oil revenues. I don’t believe that. So, the government should sell everything — the oil and gas sector. I have been making this point since 1999 when I was head of the Bureau of Public Enterprises (BPE). I have not changed my mind.
“The government should get out of whatever is left of electricity. Leave it to the private sector. Maintain the environment. The money will come. Nothing has changed for NNPC other than adding L to it for the limited. They are still taking our money. They are still declaring profits that we don’t see the dividends.”
Speaking further, el-Rufa’i said the sectors doing well in the country like entertainment, telecoms, fintech and others have no government involvement.
Guardian







Auto
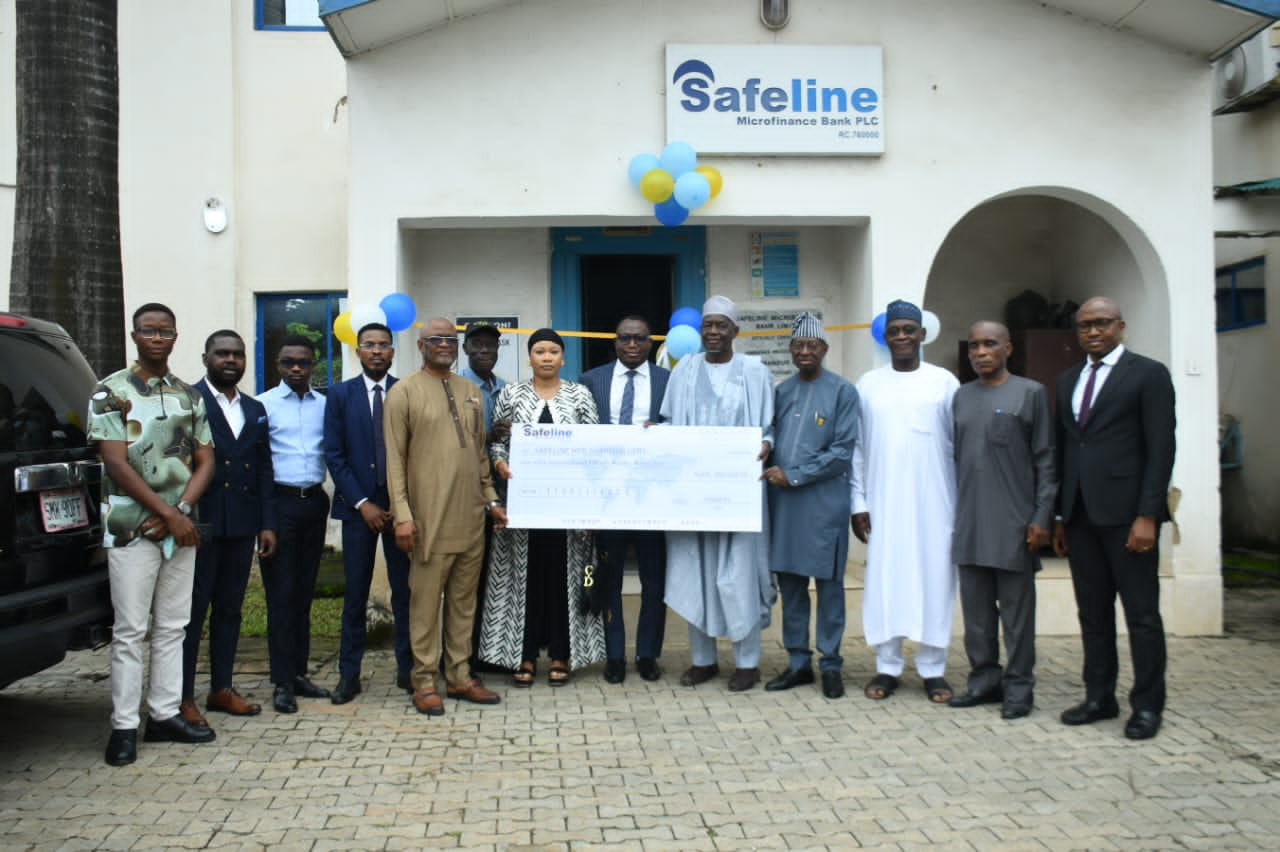
FRSC hands over Safeline Bank to ROBOPAY, targets digital financial transformation
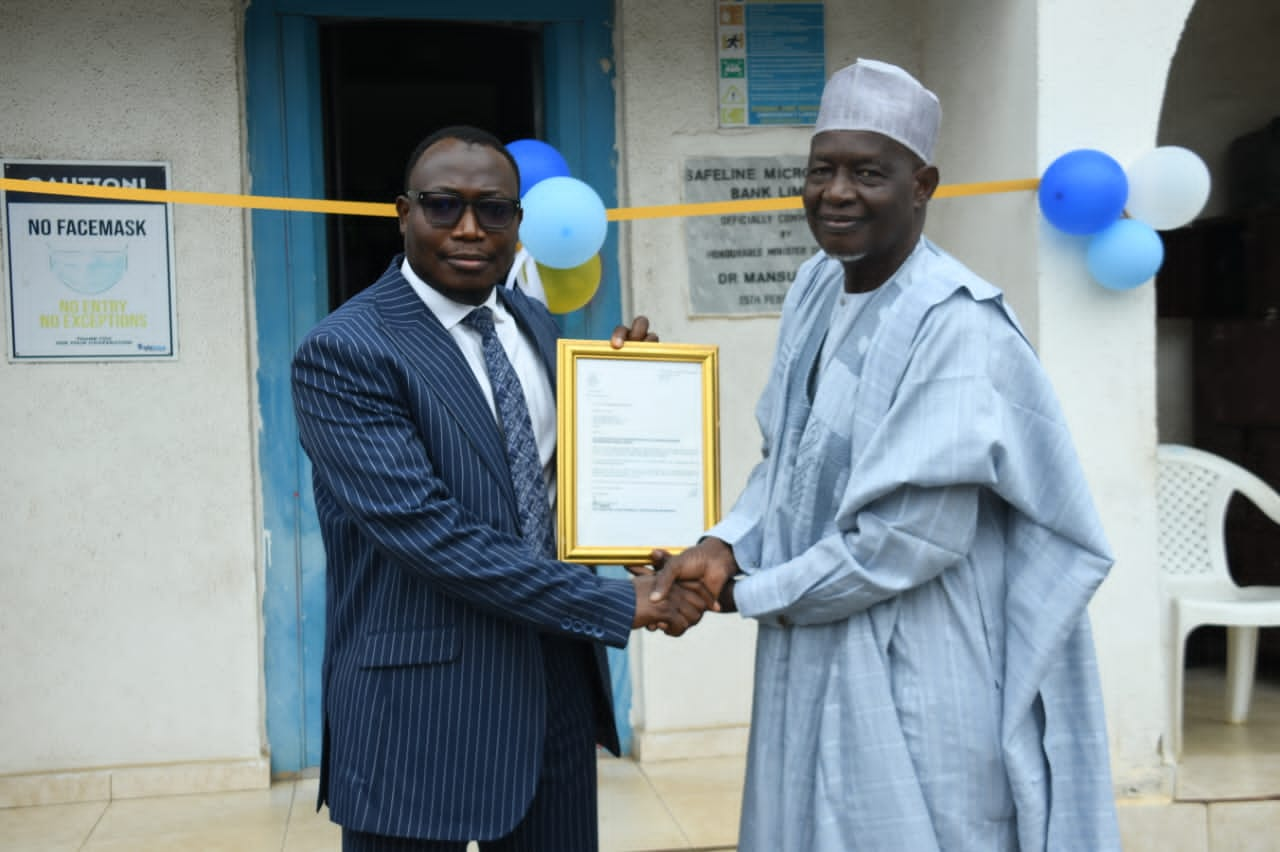
FRSC hands over Safeline Bank to ROBOPAY, targets digital financial transformation
The Federal Road Safety Corps (FRSC) has handed over ownership of Safeline Microfinance Bank to ROBOPAY NIG. LTD., paving the way for a major recapitalisation and technology-driven transformation of the financial institution.
The divestment, which took place on Monday, October 5, 2026, at the bank’s premises in Abuja, is expected to reposition Safeline Microfinance Bank for stronger competitiveness, improved service delivery and sustainable growth in Nigeria’s rapidly evolving financial services sector.
The development, according to a statement by the Corps Public Education Officer, Osondu Ohaeri, is part of the strategic efforts under the leadership of the Corps Marshal, Shehu Mohammed, to reposition the institution for greater efficiency and competitiveness.
Safeline Microfinance Bank was established by the FRSC to provide financial services and opportunities to members of the Corps and other stakeholders.
Speaking at the handover ceremony, Chairman of the Board of Safeline Microfinance Bank, Ibrahim Babagana, a Deputy Corps Marshal (Rtd.), said the decision to divest the bank followed a careful assessment of the prevailing regulatory environment and emerging government policies affecting the microfinance banking industry.
Babagana said sustaining the bank under the changing financial landscape would require substantial additional capital, greater investment in technology and enhanced human capital.
He explained that the Board therefore resolved to transfer ownership to an investor with the capacity, resources and commitment to make the required investments and place the bank on a sustainable growth trajectory.
The former FRSC chief expressed confidence in ROBOPAY, saying the company had demonstrated the competence, commitment and vision required to build on the foundation established by the Corps and take Safeline Microfinance Bank to a new level.
He identified strengthening the bank’s capital base, deploying modern technology and investing in human resources as critical priorities for its survival and competitiveness in the increasingly digital financial services market.
Responding on behalf of ROBOPAY NIG. LTD, Malam Aliyu Abiodun thanked the Board and management of Safeline Microfinance Bank for the confidence reposed in the company, describing the acquisition as a significant milestone and an opportunity to unlock the institution’s considerable potential.
Abiodun said the bank already had valuable assets, structures and an institutional foundation which the new owners would build upon through strategic investments in financial technology, capital and human resources.
He said ROBOPAY would deploy FinTech solutions to modernise the bank’s operations, improve customer experience, expand its service offerings and strengthen its competitive position within Nigeria’s financial services industry.
According to him, the new ownership would retain and leverage the institutional foundation created by the FRSC while introducing innovative technology-driven solutions capable of opening new growth opportunities for the bank.
The transaction thus signals more than a change in ownership, as it ushers Safeline Microfinance Bank into a new phase anchored on recapitalisation, digital innovation and professionalised financial services.
Both parties expressed commitment to ensuring a seamless transition, with the ultimate objective of building a stronger, more competitive and sustainable institution capable of delivering greater value to its customers and stakeholders.
Business
Tantita Operations Push Oil Export Earnings to $9.39bn in Q2
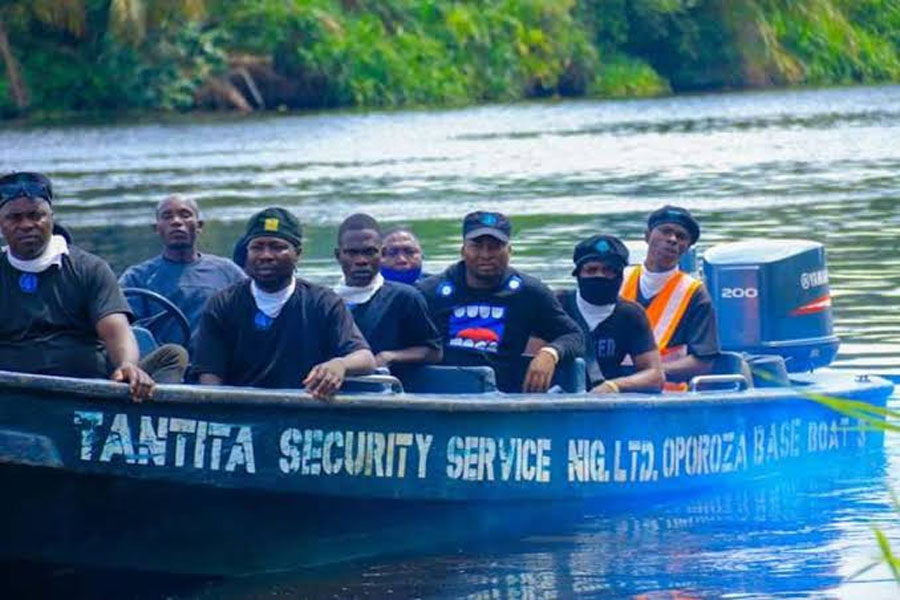
Tantita Operations Push Oil Export Earnings to $9.39bn in Q2
Nigeria’s crude oil export earnings rose to $9.39 billion in the second quarter of 2026, with improved pipeline security, higher production and greater stability in the Niger Delta supporting the stronger performance.
Provisional Balance of Payments (BOP) data showed that Nigeria’s total goods exports increased to $20.08 billion in Q2, up from $15.56 billion in the first quarter.
Crude oil exports increased by 15.78 per cent to $9.39 billion, while natural gas exports climbed by 40.15 per cent to $3.63 billion.
The improvement has renewed attention on the role of pipeline security in protecting Nigeria’s oil production and ensuring that crude reaches evacuation points and export terminals.
Among the companies involved in pipeline surveillance in the Niger Delta is Tantita Security Services Nigeria Limited (TSSNL), which was engaged by the Federal Government to protect oil pipelines and other critical petroleum infrastructure.
Tantita’s operations, carried out alongside government security agencies, have focused on tackling oil theft, illegal bunkering and pipeline vandalism and improving the security of facilities used to transport crude oil.
READ ALSO:
- Fifty Years After “Africa Has Come of Age”: A Personal Reflection on Nigeria’s Silence at the United Nations
- Family seeks N10m to free kidnapped newlywed, other victims
- Trump launches ‘Super Intelligence Force’ to keep US ahead in AI race
Industry stakeholders have linked the improved operating environment in the Niger Delta to increased crude production and stronger export performance. However, the rise in export earnings cannot be attributed to Tantita alone, as production volumes, international oil prices, investments, operational efficiency and wider government measures also influence export receipts.
The broader export figures also showed significant improvements across other sectors of the petroleum industry.
Refined petroleum product exports increased by 66.24 per cent to $3.94 billion, while non-oil exports rose by 25.30 per cent to $3.12 billion during the quarter.
At the same time, Nigeria’s crude oil imports fell sharply from $1.39 billion in Q1 to $580 million in Q2, further strengthening the country’s external position.
The stronger export performance helped push Nigeria’s current account surplus to $7.54 billion, representing a 67.93 per cent increase from the $4.49 billion recorded in Q1. The figure was also higher than the $5.17 billion recorded in Q2 2025.
The increase in the current account surplus was driven largely by higher export earnings and an improved goods account.
The rise in crude earnings also coincided with stronger production, with Nigerian crude output reaching about 1.56 million barrels per day in June 2026, excluding condensates.
The development is significant for Nigeria, which has struggled in recent years to consistently meet its production potential because of crude oil theft, pipeline vandalism, ageing infrastructure and underinvestment in the upstream sector.
Improving security around oil-producing assets has therefore become a key part of efforts to raise output and increase foreign-exchange earnings.
Tantita, led by High Chief Government Oweizide Ekpemupolo, popularly known as Tompolo, has been at the centre of the Federal Government’s pipeline surveillance arrangement in the Niger Delta.
Stakeholders, however, say sustained growth in oil earnings will require more than surveillance operations. They have called for continued investment in exploration and field development, improved infrastructure, enhanced recovery from mature fields and faster development of major deepwater projects.
The Federal Government has also been pursuing measures aimed at attracting fresh investment into Nigeria’s upstream sector, including fiscal incentives for deepwater oil and gas projects.
For Nigeria, the latest export figures offer a boost at a time when the country is seeking stronger foreign-exchange inflows, increased oil production and greater fiscal revenues.
The challenge now is to sustain the improvement by keeping petroleum infrastructure secure, reducing crude losses and ensuring that higher production translates into consistent export earnings and broader economic benefits.
Tantita Operations Push Oil Export Earnings to $9.39bn in Q2
Business
Dangote Sets 40-Month Deadline for $16bn East Africa Refinery in Kenya
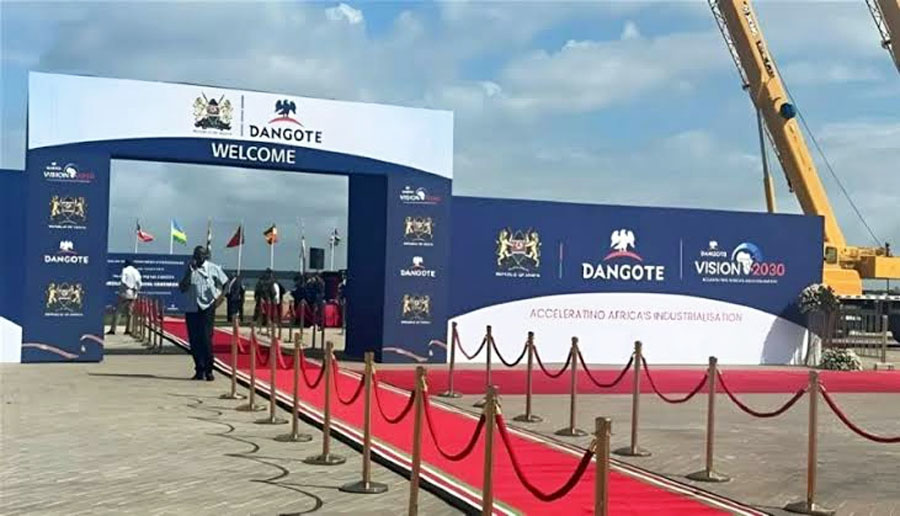
Dangote Sets 40-Month Deadline for $16bn East Africa Refinery in Kenya
Nigerian industrialist Aliko Dangote has set a 40-month completion target for his planned $16 billion East Africa refinery in Lamu, Kenya, following the official groundbreaking of the project.
Dangote and Kenyan President William Ruto broke ground for the 700,000-barrel-per-day (bpd) refinery on Wednesday, September 30, 2026, with the facility designed to supply refined petroleum products to Kenya and other countries across the region.
Dangote said the refinery would be commissioned within 40 months.
“We will come back here and commission this refinery in 40 months from today,” he said at the ceremony.
The Dangote East Africa Petroleum Refinery and Petrochemicals Complex is expected to process about 700,000 barrels of crude oil daily, making it one of the largest refining projects in Africa and, when completed, potentially the world’s largest single-train refinery.
The project is expected to produce petrol, diesel, jet fuel, polypropylene and base oil, with the products targeted at Kenya and wider East African markets. Dangote has also said part of the refinery’s jet-fuel output could be supplied to Europe and the United Kingdom.
The facility will also include a planned 1,000-megawatt power plant, which Dangote said would provide electricity for the wider industrial complex.
READ ALSO:
- Zimbabwe Tycoon Wicknell Chivayo, Wife Among Six Killed in Helicopter Crash
- 2027: Amaechi Recalls How APC Defeated PDP, Orders ADC Mobilisation
- Adeyanju Faults Okpebholo’s Governance, Commends Edo Anti-Kidnapping Efforts
Beyond refining, the billionaire said the project would create an industrial ecosystem covering petrochemicals, logistics, engineering, marine services, manufacturing, technology and small and medium-sized enterprises.
Dangote also announced plans for a training school that would prepare 1,000 Kenyan engineering graduates for opportunities associated with the project. The wider development is expected to generate thousands of jobs across the refinery and related industries.
The project has attracted major international engineering and technology partners, with Honeywell Technologies providing process technologies, licensing, engineering services, catalysts, equipment and digital solutions.
The use of established designs and experience from Dangote’s Nigerian refinery is expected to shorten the development schedule compared with a typical new refinery.
Engineers India Limited is also involved in the project under a major engineering and project-management contract.
Dangote’s Kenyan project is modelled partly on the experience of his 650,000-bpd refinery in Lagos, with the new facility expected to draw on technology and engineering experience gained from the Nigerian plant.
The refinery is expected to source crude from Uganda and other African producers, while serving a market extending beyond Kenya to countries including Uganda, Rwanda, Tanzania, Ethiopia and South Sudan.
Regional leaders who attended the groundbreaking included Ugandan President Yoweri Museveni and Ethiopian Prime Minister Abiy Ahmed, alongside other African leaders and former Nigerian President Olusegun Obasanjo.
President Ruto described the project as an investment in energy security, industrialisation and regional integration, while stressing the importance of ensuring that Kenyan citizens benefit from the employment and training opportunities created by the refinery.
Dangote has also proposed allowing governments in the region to take a combined 30 per cent stake in the refinery, potentially giving participating countries an opportunity to benefit financially from the project.
However, the project faces a legal challenge over the land on which it is being developed. A Kenyan court ordered parties to maintain the status quo over a disputed parcel in Lamu after residents challenged the development, citing ancestral land claims and other concerns.
Environmental concerns have also been raised over the potential impact of the project on the coastal ecosystem and the wider Lamu area.
Despite the legal and environmental issues, Dangote has said the project will proceed.
Once completed, the $16 billion Kenya refinery is expected to increase refining capacity in East Africa, reduce dependence on imported petroleum products and support the region’s broader industrialisation drive.
Dangote Sets 40-Month Deadline for $16bn East Africa Refinery in Kenya
-
 metro2 days ago
‘I Thought I Was Dead’ — Hairstylist’s Daring Escape From Kidnappers After Benin-Ore Ambush
-
 metro1 day ago
Tragedy Strikes FMC: Medical Director Loses Two Daughters—A Doctor and a Pharmacist—Within 48 Hours
-
 metro1 day ago
Transporters Urge IGP Disu to Arrest Illegal Highway Tax Collectors
-
 metro2 days ago
Court Restricts Osun Accounts Over $13.9m Arbitration Award
-
 Politics1 day ago
2027: Soludo Govt Accuses Peter Obi Of Plot To Destroy APGA
-
 metro1 day ago
Army, DSS, Amotekun Kill ISWAP Commander Planning Attacks in Southern Nigeria
-
 Entertainment2 days ago
“Sometimes, I Wonder Why I Married My Husband” — Omotola
-
 News1 day ago
BREAKING: Many Feared Dead as Helicopter Crashes in Ondo Community